Choosing the right lender in Chile can impact your financial health for years. Many people wonder if a credit union like Coopeuch offers better terms for consumer loans compared to a traditional commercial bank.
Understanding these differences is key for anyone considering their next financial step.
Understanding Consumer Loans in Chile
Consumer loans are widely used to cover expenses such as home improvements, travel, or covering urgent needs. In Chile, both credit unions and commercial banks grant these loans. However, the way each operates shows clear distinctions.
Consumer loans typically have fixed payment schedules. Borrowers receive a lump sum and repay it over a set period with interest.
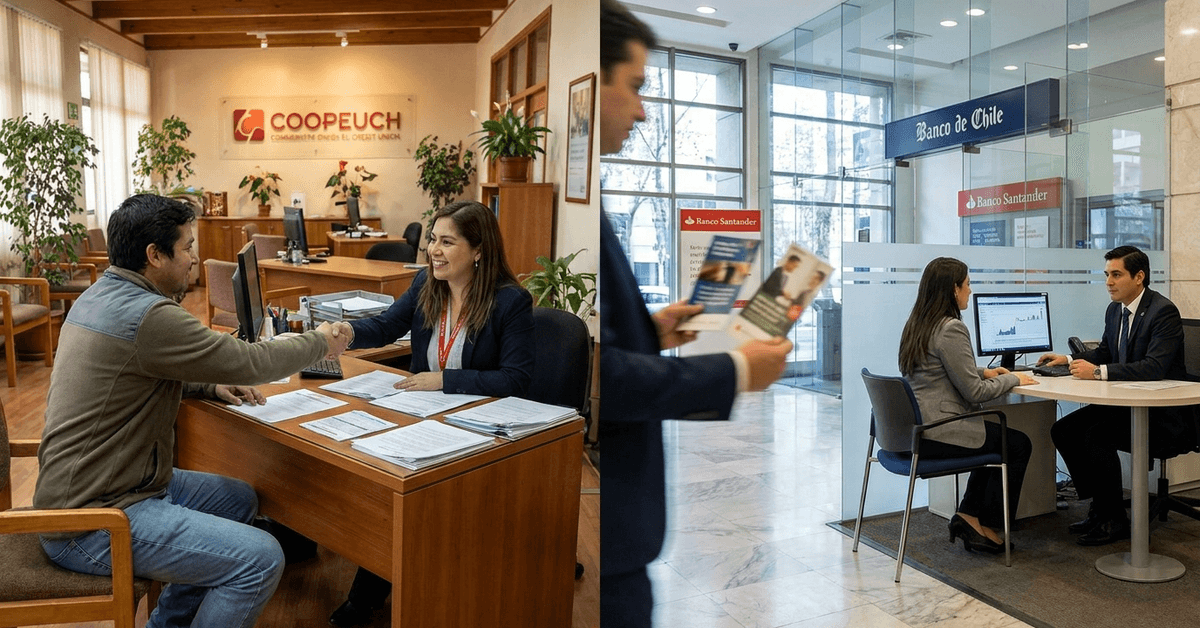
What Sets Coopeuch Apart from Commercial Banks?
Coopeuch is the largest credit union in Chile. It operates on a cooperative model, where members also become partial owners. This structure differentiates credit unions from profit-driven banks.
Commercial banks, like Banco de Chile or Banco Santander, prioritize shareholder returns. They have broader product and service portfolios but tend to maintain stricter risk criteria.
Membership-Based Focus
Joining Coopeuch means becoming a member with voting rights. This often leads to a more community-focused approach and a share in profits if the union performs well.
Banks have customers, not members. Their focus is primarily on maximizing profit through financial products.
Interest Rate Differences
Coopeuch frequently offers lower average interest rates for loans than many national banks. Members may access special seasonal promotions as well.
Banks sometimes match these rates for select clients but commonly stick to standard lending rates found on the market.
Why Consumers in Chile Choose Credit Union Loans
Many Chilean consumers consider credit union loans for their member-focused approach, flexible terms, and potential cost advantages compared with traditional banks.
Better Access for Diverse Profiles
Many people without a long credit history or with mid-level income find it easier to get approval at Coopeuch. Flexible evaluation criteria benefit freelancers and independent workers.
Banks often request longstanding work contracts and may be selective with first-time borrowers.
Flexible Repayment Terms
Coopeuch may offer extended repayment periods, giving borrowers room to manage cash flow. Some commercial banks enforce stricter deadlines or fewer installment options.
Transparent Fee Structures
Credit unions, by law, must be transparent with their fees and conditions. This transparency builds greater trust among members.
Banks have more complex pricing, with hidden commissions sometimes surprising customers later in the process.
Member Support and Financial Education
Coopeuch invests in financial education for its members. Workshops and online tools help members understand loans, interest, and budgeting basics.
While some banks have begun to develop educational content, their focus generally remains on product sales.
Main Features of Coopeuch Consumer Loans
Coopeuch consumer loans combine cooperative membership benefits, varied repayment options, and personalized credit conditions, giving eligible borrowers another way to finance personal needs.
- Online application through the Coopeuch website
- Flexible terms from 6 to 60 months
- Upfront insurance and fee disclosure
- Personalized rates based on membership and payment history
Loan Process: A Step-by-Step Overview
The loan process follows several key stages, from checking eligibility and preparing documents to credit assessment, offer review, and final approval.
- Apply online or visit a Coopeuch branch in Santiago, Valparaíso, or Concepción
- Submit basic documentation: ID, proof of income, and address
- Review personalized loan offers presented in real time
- Choose terms, sign digitally, and receive funds within 24 hours for most approved loans
How Commercial Bank Consumer Loans Differ
Commercial bank consumer loans often differ in eligibility standards, pricing, digital services, loan limits, and repayment structures compared with cooperative lenders.
Wider Product Range
Banks may offer bundled packages with insurance, credit cards, or overdraft protection alongside loans. This increases options but adds complexity to the decision process.
App and Online Banking Tools
Banks like Banco Estado and Banco de Chile have robust mobile banking apps. These apps allow customers to manage loans, set up payments, and monitor balances conveniently.
Stricter Approval Criteria
Banks routinely check credit scores and employment stability before granting loans. Some require higher minimum incomes or additional guarantees.
Eligibility: Who Can Access Each Option?
Eligibility can vary between cooperatives and commercial banks, with income, credit history, membership status, and repayment capacity shaping access to each option.
| Requirement | Coopeuch | Commercial Banks |
|---|---|---|
| Minimum income | Low to moderate | Moderate to high |
| Credit history | Flexible for new borrowers | Strict requirements |
| Residency | Valid Chilean ID or foreign resident card | Chilean citizens or long-term residents |
Top Mobile Apps and Tools for Loan Management
Mobile apps and digital tools can simplify loan management by helping borrowers track payments, monitor balances, review terms, and access support more easily.
- Coopeuch Móvil for loan tracking, document uploads, and account management
- BancoEstado’s app for managing commercial bank loans and payment reminders
- Portal Cliente by Santander for tracking repayments and accessing loan information
Real-World Examples: Comparing Monthly Payments
Suppose two borrowers in Valdivia each request a 1,000,000 CLP loan for 24 months. One uses Coopeuch, the other chooses Banco de Chile.
The Coopeuch member may secure a lower APR and monthly payment due to cooperative pricing. The commercial bank borrower might face higher insurance charges but could access bundled products.
Exact differences depend on credit scores, existing relationships, and negotiation. However, reports suggest average savings of 8-15% in total cost for Coopeuch members.
6 Tips for Choosing Between Coopeuch and Commercial Banks
Choosing between Coopeuch and a commercial bank requires more than comparing advertised rates. Borrowers should consider total cost, eligibility, repayment flexibility, digital support, and overall convenience.
1. Compare the Full Cost
Look beyond the headline interest rate. Compare the CAE, fees, insurance costs, and total amount repayable to understand the real borrowing expense.
2. Review Eligibility Requirements
Each lender uses different approval criteria. Income stability, credit history, existing debts, and Coopeuch membership requirements may influence eligibility.
3. Check Repayment Flexibility
Ask about early repayment, payment adjustments, and restructuring options. Confirm whether additional fees or conditions apply.
4. Evaluate Digital Services
Compare mobile apps, online banking tools, payment tracking, and digital customer support. Convenient technology can make ongoing loan management easier.
5. Consider Customer Experiences
Reviews and financial education forums may provide useful insight into customer service and common issues. Treat individual experiences as supplementary information rather than guarantees.
6. Focus on Long-Term Affordability
A lower monthly installment does not always mean a cheaper loan. Compare repayment periods and total costs to ensure the loan remains manageable throughout its term.
Conclusion: Navigating Loan Options in Chile
Choosing between Coopeuch and commercial banks depends on cost, flexibility, accessibility, and service preferences.
Coopeuch may suit borrowers seeking a member-focused approach, while banks often provide broader products and digital tools. Compare the CAE, fees, repayment terms, and total cost before deciding.